When it comes to buying property, one of the most important decisions you’ll make is choosing the right ownership structure. Buying in your own name, buying with someone else and buying through a company can look similar during the property search. The differences become clearer when you apply for finance, work out who’s responsible for the costs or eventually sell. Each option has its own set of pros and cons that can significantly affect your financial and legal responsibilities.
If you’re weighing up buying as an individual or through a company, here’s what changes in practice. We’ll also cover joint ventures, trusts and self-managed super funds (SMSFs), along with the questions to take to your advisers before you sign.
Buying Property as an Individual
Buying as an individual (or with a partner or spouse) is typically the most common and straightforward way to purchase property. The process is simpler compared to buying through a company or trust, and it’s usually the cheapest option in terms of upfront costs. When you buy in your own name, you generally hold the property directly. If you take out a loan in your own name, you’re personally responsible for repaying it. Ask your lender or mortgage broker to explain what you’re liable for under the loan.
If you’re buying your first home in NSW, the First Home Owner Grant and the First Home Buyers Assistance Scheme are separate. The assistance scheme provides transfer duty relief for eligible buyers. Check the rules for the property you’re considering, especially if you plan to rent it out. Service NSW’s First Home Buyers Assistance Scheme guide
Ask your accountant: How would the rental income, expenses and any gain on sale be treated if I bought in my own name?
Buying Property as a Company
When a company buys property in its own capacity, the company owns it. The company has its own reporting and administration obligations. If you’re setting up a company for the purchase, ask your accountant what it would cost to establish and maintain. There are also two differences worth checking upfront. First, if the company borrows, the lender may ask you for a personal guarantee. Ask what you’d be personally liable for under that guarantee. Second, companies generally can’t access the CGT discount available to eligible individuals. Ask your accountant to explain how a future sale would be treated under each option.
Ask your advisers: Who would own the property, who would owe the money and what would happen if the company sold it?
Buying Property in a Joint Venture
A joint venture brings two or more parties together to buy a property or undertake a project. For example, one person might contribute more of the deposit while the other takes responsibility for managing a renovation. How you record those contributions, and how you hold the property, are separate questions to work through with your solicitor. Buying property in a joint venture (JV) has many benefits, but it’s important to understand the risks involved before you take the plunge.
Before buying together, talk through who pays if costs run over budget, how decisions will be made and what happens if one person wants to sell before the other. If you’ll own the property directly together, ask your solicitor to explain the difference between joint tenants and tenants in common.
Ask your solicitor: If one of us wants out, how would we value their share and what would happen to the loan?
Ask your accountant: What are the tax implications of a JV? It’s essential to understand how your share of the profits or losses will be taxed.
Buying Property Through a Trust
When a property is bought through a trust, the trustee holds legal title in that capacity. The trust deed sets out the trustee’s powers and how the trust operates. Ask your solicitor to confirm who would act as trustee and how the buyer should be named on the contract.
From a tax and cost perspective, ask your accountant how rental income, losses and any gain on sale would be treated, and whether the structure would affect land tax in the state where you’re buying. If you’ll need finance, ask your mortgage broker how the lender would assess the trust and whether it would require guarantees.
Ask your advisers: What would this structure cost to set up and run, and how would it work if we sold the property later?
Buying Property Through a Self-Managed Super Fund
If you’re looking at a property purchase through an SMSF, the type of property, who you buy it from, who will use it and how the fund will pay for it all matter.
Residential property
An SMSF generally can’t buy a residential property from a fund member or a related party. Fund members and their related parties also can’t live in it or rent it from the fund.
Commercial property
Different rules can apply if the premises qualify as ‘business real property’. For example, the fund may be able to buy eligible business premises from a related party or lease them to a related business, subject to specific conditions and market terms. Ask your solicitor to check the particular property and proposed lease.
Borrowing
If the fund needs a loan, the purchase is generally financed through a limited recourse borrowing arrangement (LRBA). The rules generally require a single asset, so flag properties on multiple titles early. Ask your broker what deposit the lender requires and whether it will lend on the specific property. Have your solicitor confirm the contract details before you sign.
Renovations
Under an LRBA, borrowed funds can generally be used for repairs and maintenance, while improvements need another source of funding. Even when the fund uses its own money, work that fundamentally changes the asset can create issues while the borrowing arrangement is in place. If the purchase depends on a major renovation or redevelopment, raise it with your advisers before making an offer.
If you’re deciding whether to set up an SMSF or use an existing one to buy property, speak with a financial adviser who is authorised to advise on SMSFs. ASIC’s Moneysmart guide to SMSFs and property · ATO ruling on SMSF borrowing arrangements
How Sharp Property Buyers Can Help
The ownership structure can shape the property brief, and the best option for you depends on your individual circumstances. You’ll need to account for a number of factors, including your financial goals, your investment strategy, your tax situation, and your risk tolerance. If your lender has restrictions on the type of property it will finance, or your solicitor has flagged something to check about the title, we can factor that into the search from day one. Once you’ve confirmed how you’ll buy with your advisers, we can help you find, assess and negotiate the purchase of a property that fits your brief. If you’re planning your next purchase, get in touch with our team.
This article is for general information only and does not constitute legal, tax or financial advice. We strongly recommend speaking with appropriately qualified advisers before deciding how to structure your property purchase.
Property News & Tips
Buying Property as a Company or an Individual
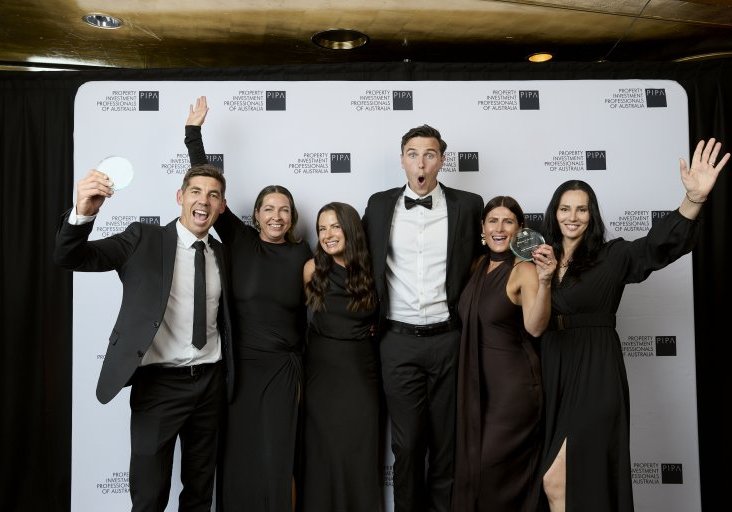
Double Recognition at the 2026 PIPA Awards
The Best Child-Friendly Places to Dine on the Central Coast
Navigating the Central Coast Rental Market
Why Sydneysiders Are Moving to the Central Coast

Central Coast Schools Guide: Top-Performing Primary and High Schools

9 Things to Consider When Buying a Central Coast Acreage Property
Best Emerging Suburbs on the Central Coast: Where Property Growth Is Happening in 2026
I want to make sure my clients are buying the best possible property available for them.
Matt Sharp - Director
The extensive history of successful property acquisitions and investments we’ve facilitated speaks volumes about our prowess. Our track record showcases a consistent pattern of achievements that underscore our ability to turn clients’ dreams into reality.
To learn more about our full-service packages, contact us today.